

How a High-Net-Worth Business Owner Secured a High-Street Mortgage with Missed Payments.
Executive Summary
High-earning entrepreneurs with minor administrative credit slip-ups often face instant rejections from automated high-street algorithms. By presenting the holistic financial strength of a high-net-worth business owner to a manual-underwriting specialist, First Select Mortgage Brokers secured a competitive high-street rate without penalty terms.
The Hook: High Net Worth, Low Algorithm Score
Running a thriving business requires absolute focus, often at the expense of personal administrative tasks. For one successful entrepreneur, a demanding work schedule and frequent travel meant that managing day-to-day personal administration sometimes fell through the cracks.
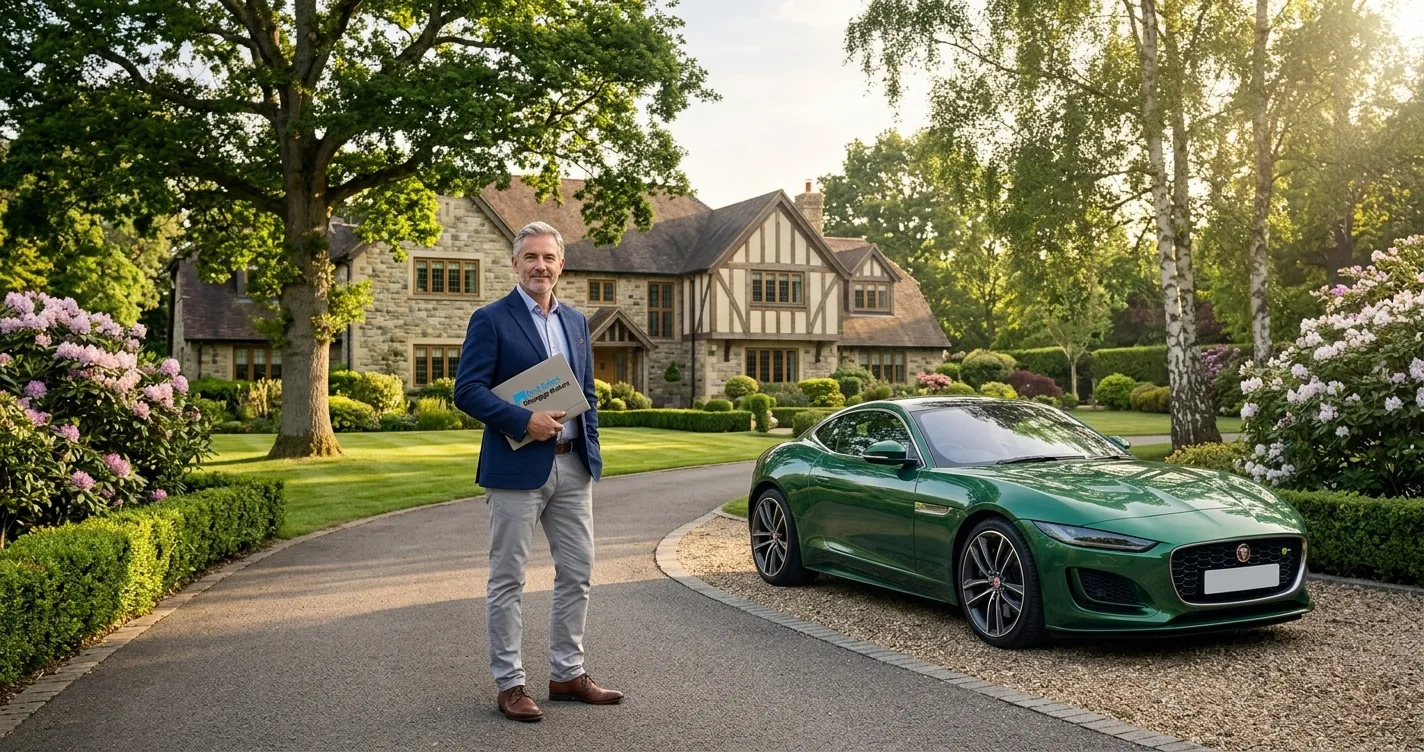
Despite generating substantial income and enjoying a luxury lifestyle—complete with high-performance sports cars and frequent international travel—his personal credit file reflected the occasional late payment and missed utility bill. When it came time to secure financing for a major residential purchase, he assumed his 20-year relationship with his primary bank would count for everything.
He was mistaken. Automated retail bank processes do not assess character or net worth; they process raw credit scores. The bank rejected his application out of hand.
The Obstacle: The High-Street Credit Wall
High-street lenders operate primarily on automated credit-scoring models. These rigid algorithms operate on binary logic:
[Late/Missed Payments Detected] ➔ [Automated System Flag] ➔ [Instant Mortgage Rejection]
This framework creates significant hurdles for high-net-worth individuals:
- Algorithmic Bias: Automated scorecards treat an accidental late payment from a multi-millionaire the same as an un-managed default from a distressed debtor.
- Complex Income Integration: Retained business earnings and dividend structures require manual analysis rather than standard automated income calculators.
- Lifestyle Footprint: Substantial discretionary spending on luxury assets can trigger misaligned affordability flags when processed through standard consumer engines.
To a retail bank, the client looked like a high-risk debtor. In reality, he was a highly solvent borrower with an organisational oversight.
The Engineering: Restructuring the Credit Narrative
Realising that standard application routes would continually hit automated rejections, the client approached Claire at First Select Mortgage Brokers.
Claire bypassed standard computer-led underwriting channels, focusing instead on manual underwriting teams within specialist divisions of high-street banks. Her approach relied on three strategic steps:
| Strategic Phase | Execution & Solution |
| 1. Paperwork Consolidation | Re-organized company accounts, personal bank statements, and tax overviews to establish absolute proof of affordability. |
| 2. Contextual Advocacy | Documented that late payments coincided directly with heavy business travel periods, proving negligence, not insolvency. |
| 3. Lender Selection | Targeted high-street lenders possessing specialized manual underwriting desks trained to evaluate holistic net worth. |
Claire presented the full narrative directly to senior credit managers. By pairing proof of substantial liquidity alongside clear context for the administrative oversights, she demonstrated that the client posed negligible financial risk.
The Outcome & Key Takeaway
The lender agreed to override the initial automated credit score flag, approving the full mortgage at standard high-street rates on highly competitive terms.
[Algorithmic Rejection] ➔ [Manual Expert Representation] ➔ [High-Street Approval]
- Key Takeaway: A computer-generated “no” from a primary bank is rarely the final word. When complex income or credit anomalies exist, securing financing requires placing your application before a human underwriter who can evaluate real risk rather than a digital scorecard.
Disclosure & Privacy
The above case study is a genuine client of First Select Mortgage Brokers. Exact details of the clients situation have been modified or changed very slightly to protect the clients privacy.
Our team of experts are ready and waiting to help. Contact the team below:
Phone: 0161 393 1575 // 07780 446 937
Email: hello@firstselectfs.co.uk
Visit our Contact Us page to make a formal enquiry
Visit us on our Social Channels:
FCA Risk Warning:
YOUR HOME OR OTHER PROPERTY CAN BE REPOSSESSED IF YOU FAIL TO KEEP UP REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT.


