Archives 2026

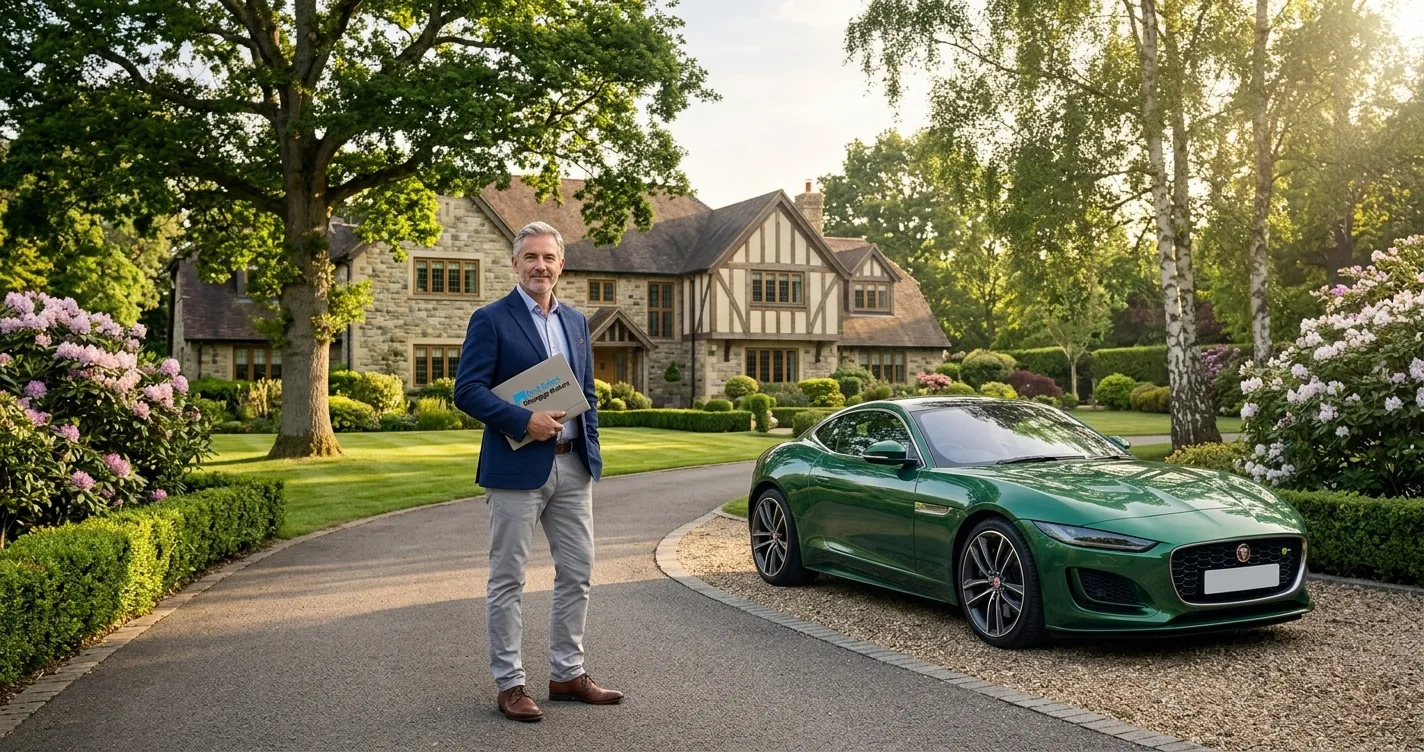
Business owner stood outside a luxury country home. Jaguar sports car on the drive way. He is aged 50 and is dressed smart holding a folder.
How a High-Net-Worth Business Owner Secured a High-Street Mortgage with Missed Payments.

Executive Summary

High-earning entrepreneurs with minor administrative credit slip-ups often face instant rejections from automated high-street algorithms. By presenting the holistic financial strength of a high-net-worth business owner to a manual-underwriting specialist, First Select Mortgage Brokers secured a competitive high-street rate without penalty terms.

The Hook: High Net Worth, Low Algorithm Score

Running a thriving business requires absolute focus, often at the expense of personal administrative tasks. For one successful entrepreneur, a demanding work schedule and frequent travel meant that managing day-to-day personal administration sometimes fell through the cracks.

Despite generating substantial income and enjoying a luxury lifestyle—complete with high-performance sports cars and frequent international travel—his personal credit file reflected the occasional late payment and missed utility bill. When it came time to secure financing for a major residential purchase, he assumed his 20-year relationship with his primary bank would count for everything.

He was mistaken. Automated retail bank processes do not assess character or net worth; they process raw credit scores. The bank rejected his application out of hand.

The Obstacle: The High-Street Credit Wall

High-street lenders operate primarily on automated credit-scoring models. These rigid algorithms operate on binary logic:

[Late/Missed Payments Detected] ➔ [Automated System Flag] ➔ [Instant Mortgage Rejection]

This framework creates significant hurdles for high-net-worth individuals:

  • Algorithmic Bias: Automated scorecards treat an accidental late payment from a multi-millionaire the same as an un-managed default from a distressed debtor.
  • Complex Income Integration: Retained business earnings and dividend structures require manual analysis rather than standard automated income calculators.
  • Lifestyle Footprint: Substantial discretionary spending on luxury assets can trigger misaligned affordability flags when processed through standard consumer engines.

To a retail bank, the client looked like a high-risk debtor. In reality, he was a highly solvent borrower with an organisational oversight.

The Engineering: Restructuring the Credit Narrative

Realising that standard application routes would continually hit automated rejections, the client approached Claire at First Select Mortgage Brokers.

Claire bypassed standard computer-led underwriting channels, focusing instead on manual underwriting teams within specialist divisions of high-street banks. Her approach relied on three strategic steps:

Strategic PhaseExecution & Solution
1. Paperwork ConsolidationRe-organized company accounts, personal bank statements, and tax overviews to establish absolute proof of affordability.
2. Contextual AdvocacyDocumented that late payments coincided directly with heavy business travel periods, proving negligence, not insolvency.
3. Lender SelectionTargeted high-street lenders possessing specialized manual underwriting desks trained to evaluate holistic net worth.

Claire presented the full narrative directly to senior credit managers. By pairing proof of substantial liquidity alongside clear context for the administrative oversights, she demonstrated that the client posed negligible financial risk.

The Outcome & Key Takeaway

The lender agreed to override the initial automated credit score flag, approving the full mortgage at standard high-street rates on highly competitive terms.

[Algorithmic Rejection] ➔ [Manual Expert Representation] ➔ [High-Street Approval]
  • Key Takeaway: A computer-generated “no” from a primary bank is rarely the final word. When complex income or credit anomalies exist, securing financing requires placing your application before a human underwriter who can evaluate real risk rather than a digital scorecard.

Disclosure & Privacy

The above case study is a genuine client of First Select Mortgage Brokers. Exact details of the clients situation have been modified or changed very slightly to protect the clients privacy.

Our team of experts are ready and waiting to help. Contact the team below:

Phone: 0161 393 1575 // 07780 446 937

Email: hello@firstselectfs.co.uk

Visit our Contact Us page to make a formal enquiry

Visit us on our Social Channels:

Facebook

Linkedin

Instagram

FCA Risk Warning:

YOUR HOME OR OTHER PROPERTY CAN BE REPOSSESSED IF YOU FAIL TO KEEP UP REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT.
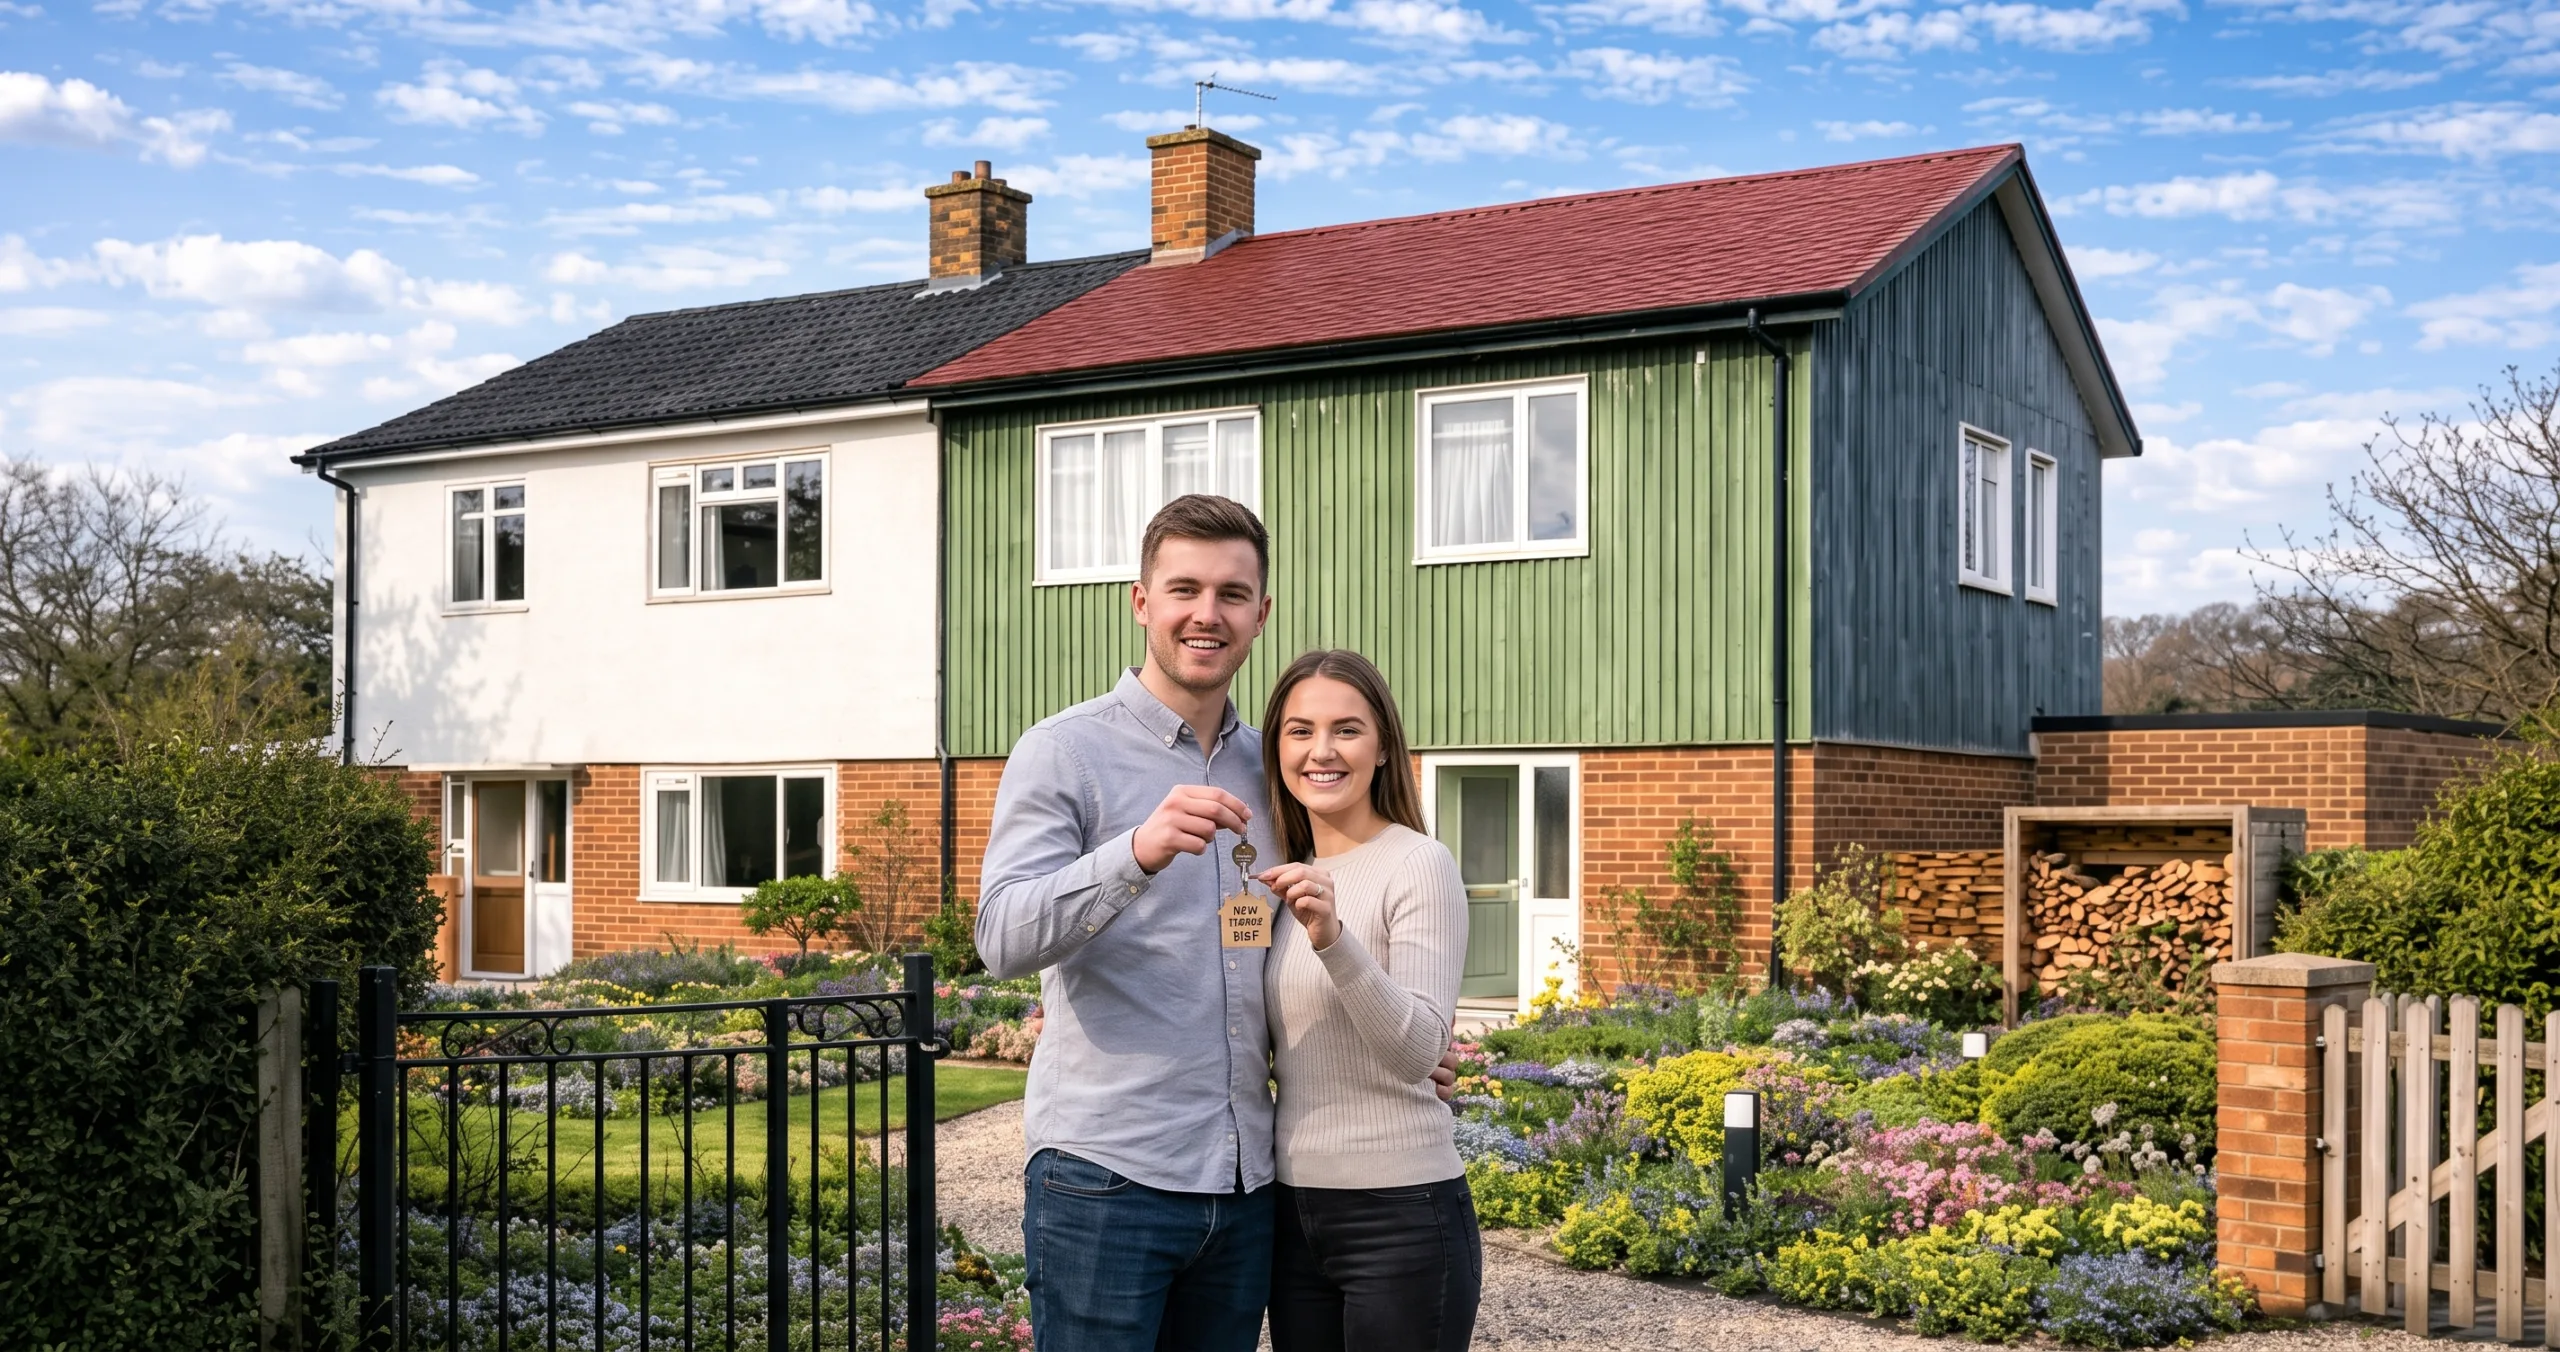
Young couple holding their house keys in front of a BISF house. They are both happy and proud to be stood outside their new home.
How We Secured a High-Street Mortgage for a BISF Metal-Framed Property for First Time Buyers

Summary:

Securing a mortgage on a British Iron and Steel Federation (BISF) steel-framed property often pushes buyers toward expensive specialist lenders due to standard high-street rejections. First Select Mortgage Brokers navigated complex lender underwriting parameters to secure a high-street mortgage at a competitive low rate with a minimal deposit for two first-time buyers.

The Goal: A First Step on the Property Ladder

For first-time buyers early in their careers, stepping onto the property ladder is already a major milestone. Our clients found an affordable home that suited their budget perfectly, allowing them to make the leap from renting to homeownership without overstretching their modest salaries.

However, the transaction carried high stakes. With limited savings, they needed a low-deposit mortgage at a competitive high-street interest rate to ensure their monthly outgoings remained manageable.

The Obstacle: The “Impassable Road” of BISF Construction

The property was a British Iron and Steel Federation (BISF) home—a popular form of post-war prefabricated steel-framed construction. Think of property underwriting like a conveyor belt: high-street lenders prefer standard brick-and-mortar homes because they are straightforward to value and resell. When a non-standard construction type like a metal frame comes down the belt, automatic systems often flag it and halt the process.

Most mainstream banks decline BISF properties outright or demand extensive, costly structural surveys alongside higher deposit requirements. Facing these rejections, the buyers feared their only route forward was a specialist lender.

Standard High-Street Path:   [ BISF Metal Frame ] ──> [ Automatic Underwriting Decline ]
Specialist Lender Path:      [ Higher Deposit Required ] + [ Elevated Interest Rates ]

Whilst specialist lenders can often provide excellent solutions to lending challenges, relying on a specialist lender in this situation would mean:

  • Higher Interest Rates: Significantly increasing monthly payments.
  • Larger Deposit Requirements: Forcing the buyers to delay the purchase to save more capital.
  • Added Financial Stress: Straining a modest budget at the very start of their financial journey.

The Engineering: Securing Mainstream Approval

Rather than accepting a high-cost specialist product, First Select restructured the application strategy from the ground up. Non-standard construction approval is not about changing the property; it is about selecting the exact lender whose criteria matrix accepts the specific structural framework.

First Select executed a three-step placement strategy:

  • Granular Criteria Matching: We filtered the entire mortgage market to isolate the select group of high-street banks whose underwriting guidelines explicitly accept BISF properties without imposing penalizing terms.
  • Pre-Application Surveyor Engagement: We engaged directly with panel surveyors prior to submission to ensure the property met the specific structural conditions required by the chosen bank.
  • Income & LTV Optimization: We packaged the clients’ modest income streams alongside a low-deposit structure (90% LTV), presenting a pristine credit profile to offset the non-standard nature of the building.

By carefully matching the physical properties of the building to the precise risk appetite of a mainstream lender, we bypassed the need for expensive secondary market financing.

The Outcome & Key Takeaway

First Select successfully secured a full mortgage offer with a tier-one high-street bank, delivering a outcome that kept the clients’ homeownership dream intact and affordable.

  • Deposit: 10% (90% LTV)
  • Interest Rate: Market-leading high-street fixed rate
  • Turnaround Time: Full offer issued in 12 working days

Key Takeaway for Buyers: A property decline from a high-street bank is rarely a final “no”—it is often simply a sign that your property type does not fit that specific bank’s automated algorithms. Specialist guidance can help you find mainstream rates on non-standard homes.

Disclosure & Privacy

The above case study is a genuine client of First Select Mortgage Brokers. Exact details of the clients situation have been modified or changed very slightly to protect the clients privacy.

Our team of experts are ready and waiting to help. Contact the team below:

Phone: 0161 393 1575 // 07780 446 937

Email: hello@firstselectfs.co.uk

Visit our Contact Us page to make a formal enquiry

Visit us on our Social Channels:

Facebook

Linkedin

Instagram

FCA Risk Warning:

YOUR HOME OR OTHER PROPERTY CAN BE REPOSSESSED IF YOU FAIL TO KEEP UP REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT.

Happy single mother enjoying cup of coffee in kitchen. Toddler playing in the back ground with toys.
How to Get a Right to Buy Mortgage on a Zero-Hours Contract.

Summary:

Single mother in Manchester, purchases home under Right to Buy scheme using zero-hours contract income & working benefit income.

By looking beyond rigid, automated underwriting models, First Select Mortgage Brokers helped a hardworking single mother secure a competitive Right to Buy mortgage on a zero-hours contract. By combining variable earned income with state benefits, we turned a seemingly impossible scenario into permanent housing stability and a lasting family legacy.

Think of securing a mortgage like fitting together a complex jigsaw puzzle. If even a single piece appears misshapen, automated systems at high-street banks immediately push the board off the table.

For many hardworking families, this creates a frustrating paradox: you can reliably pay rent month after month, yet traditional algorithms classify you as “not mortgage worthy” when you try to buy the very home you live in.

The Obstacle: An Assembly Line “No”

Our client, a dedicated single mother living in her council home, was presented with a life-changing opportunity: purchase her property under the UK Government’s Right to Buy scheme. Exercising this right would give her children permanent stability and an asset to inherit in the future.

However, her financial layout didn’t fit the standard high-street mould:

  • Income Structure: Employed on a zero-hours contract, supplemented by Child Benefit and Working Tax Credits.
  • Credit Profile: Satisfactory, with a consistent track record of meeting commitments.
  • The Main Barrier: Multiple mortgage brokers had already turned her away, declaring her combination of zero-hours earnings and benefit income ineligible for high-street mortgage lenders.

To a standard automated system, a zero-hours contract looks like shifting sand. Most high-street lenders require a minimum 12-to-24-month unbroken history with a single employer or outright reject variable-hour contracts when state benefits form a significant portion of the total household income. After several rejections, the door to home ownership seemed firmly shut.

+-----------------------------------------------------------------------+
|                       FINANCIAL PROFILE OVERVIEW                      |
+--------------------------+--------------------------------------------+
| Scheme                   | Right to Buy                               |
| Employment Status        | Zero-Hours Contract                        |
| Supplementary Income     | Child Benefit & Working Tax Credits        |
| High-Street Verdict      | Declined (Inflexible Income Criteria)     |
| First Select Outcome     | Approved (100% LTV of Discounted Price)    |
+--------------------------+--------------------------------------------+

The Engineering: Manual Underwriting & Manual Logic

When the client reached Claire at First Select Mortgage Brokers, the approach shifted from automated box-ticking to manual underwriting logic.

  1. Evidencing Income Stability: Claire audited 12 months of payslips and bank statements to establish a solid, predictable baseline for the zero-hours earnings, demonstrating that the income was consistent despite the contractual structure.
  2. Structuring Benefit Alignment: Not all lenders treat state support equally. Claire identified a specialist lender whose criteria fully accepts Child Benefit and Working Tax Credits at 100% value alongside earned income.
  3. Leveraging the Scheme Discount: The built-in Right to Buy discount served as the equity deposit, removing the need for additional cash reserves and mitigating the lender’s loan-to-value (LTV) exposure.

By presenting a fully verified package to a manual underwriting team, Claire demonstrated that the proposed mortgage payments were actually lower than the client’s current monthly rent obligations.

The Outcome: Foundation for the Future

The lender issued a formal offer at a competitive rate, ensuring long-term monthly affordability without stretching the household budget.

MetricDetails
Transaction TypeRight to Buy Purchase
Lender TypeSpecialist Manual-Underwritten Lender
Income Assessment100% Averaged Zero-Hours + 100% State Benefits
Core ResultSecured full purchase funding with affordable monthly payments

More than just a financial transaction, securing this mortgage transformed a rental property into a permanent family asset—providing long-term security today and an inheritance for her children tomorrow.

Key Takeaway: A rejection from a computer algorithm is rarely a final answer. If your income structure is non-standard, success relies on matching your specific profile with a lender that uses human judgement rather than automated checklists.

Disclosure & Privacy

The above case study is a genuine client of First Select Mortgage Brokers. Exact details of the clients situation have been modified or changed very slightly to protect the clients privacy.

Our team of experts are ready and waiting to help. Contact the team below:

Phone: 0161 393 1575 // 07780 446 937

Email: hello@firstselectfs.co.uk

Visit our Contact Us page to make a formal enquiry

Visit us on our Social Channels:

Facebook

Linkedin

Instagram

FCA Risk Warning:

YOUR HOME OR OTHER PROPERTY CAN BE REPOSSESSED IF YOU FAIL TO KEEP UP REPAYMENTS ON YOUR MORTGAGE OR ANY OTHER LOAN SECURED AGAINST IT.